Free real estate schedule template (schedule of real estate owned)
Download the template
Free, no email required. Generated by the same engine that renders LivePFS’s lender-ready statements.
Lender-standard structure · Free to use and share · How LivePFS handles data
A real estate schedule — also called a schedule of real estate owned, or REO schedule — lists every property you own with its value, debt, and cash flow, one property at a time. Lenders request it alongside a personal financial statement whenever real estate is a meaningful part of your net worth. Download a blank REO schedule below as a PDF, an Excel workbook with live totals, or a CSV — free, no email required.
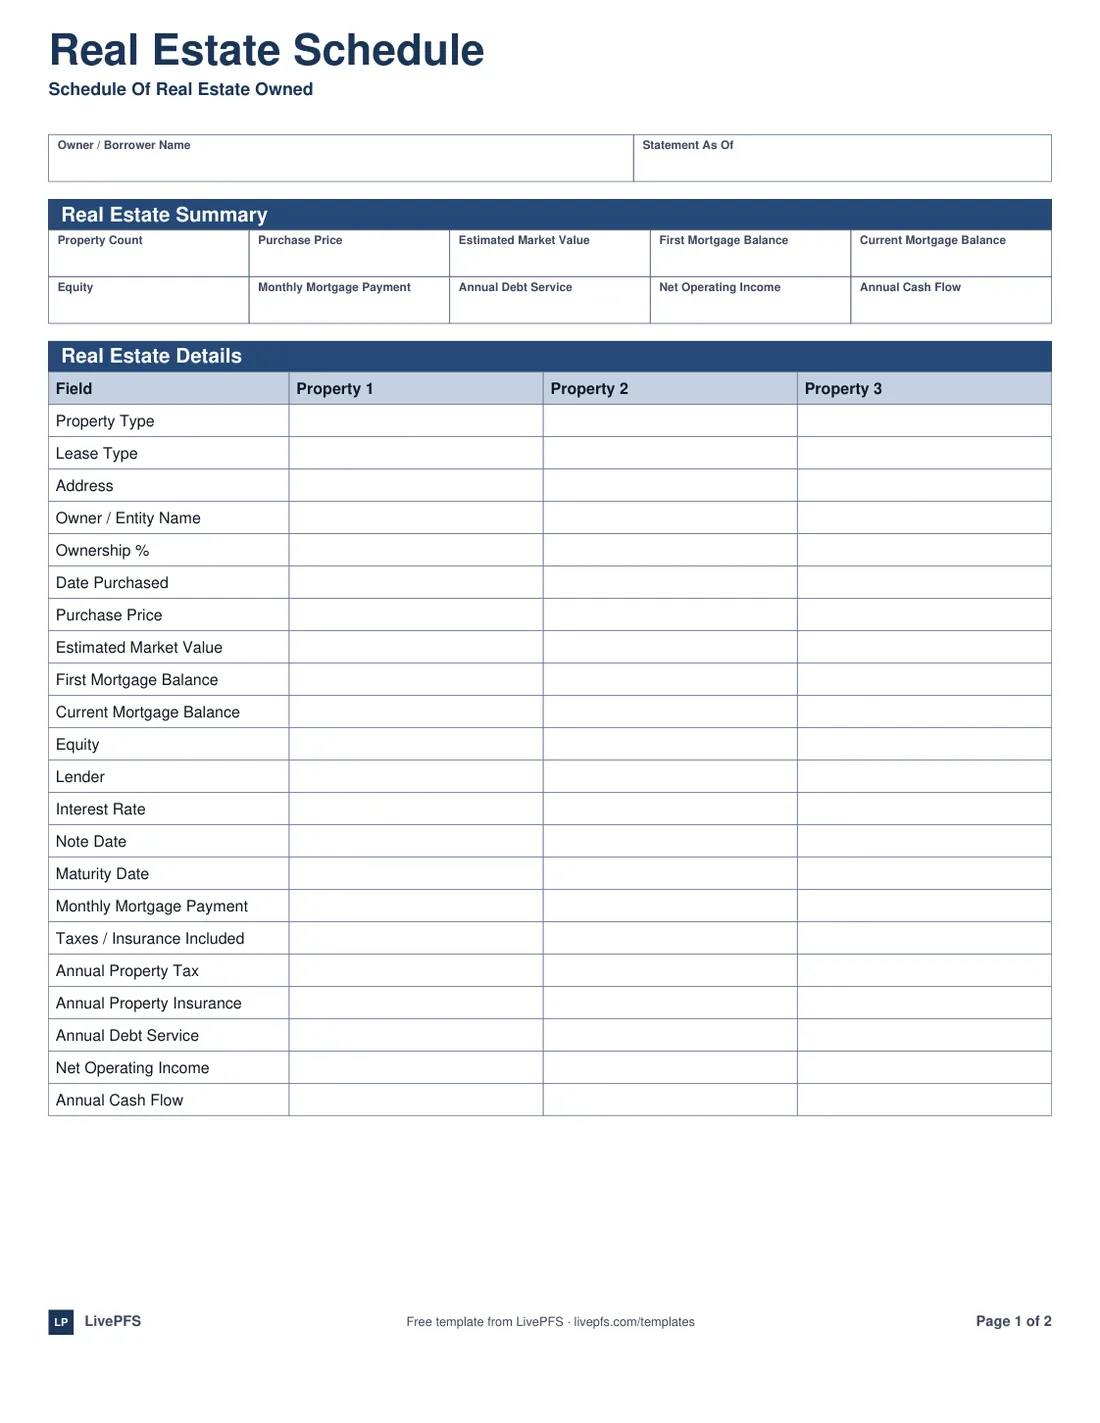
The template carries the full column set underwriters read: address, owner or entity, ownership percentage, purchase data, market value, mortgage balances and lender terms, taxes and insurance, net operating income, annual debt service, and annual cash flow — plus a portfolio summary strip for the totals a lender checks first.
What’s inside
- A portfolio summary: property count, total value, total mortgage debt, equity, debt service, NOI, and cash flow.
- Per-property detail with 22 fields — the same field list LivePFS prints on its lender-ready real estate schedule.
- Ownership columns for entity and percentage, so properties held in LLCs or partnerships report honestly.
- Income and expense rows per property: taxes, insurance, net operating income, debt service, and annual cash flow.
How to use it
- List every property you own or guarantee debt on — lenders reconcile this schedule against your credit report and mortgage statements.
- Use current market value and the current mortgage balance; equity is value minus debt, per property.
- Net operating income is rent minus operating expenses, before debt service. Annual cash flow is NOI minus annual debt service.
- For partial ownership, record the entity and your percentage rather than inventing a blended number.
- In the Excel version the Totals row computes automatically; insert extra rows above it and the sums keep covering them.
The columns, explained
Identity and ownership
Address, property type, owner or entity of record, and your ownership percentage. Properties held in LLCs or partnerships stay honest here: name the entity that holds title and your percentage, and let the lender see the structure instead of a silently blended number.
Value and debt
Purchase date and price, current market value, first and current mortgage balances, and equity (value minus total debt). The purchase columns give the lender a sanity check on your value estimate; the balance columns get reconciled against your credit report and mortgage statements.
Loan terms
Lender, interest rate, note and maturity dates, and the monthly payment (note whether taxes and insurance are escrowed in it). Maturity dates matter more than borrowers expect — a balloon coming due inside the new loan's term is exactly what an underwriter is scanning for.
Cash flow
Annual property tax, insurance, net operating income, annual debt service, and annual cash flow. These five columns turn a list of properties into an income statement per door — and they are where a schedule earns trust, because they let the reader recompute your numbers.
The three numbers underwriters compute from it
- Leverage — total mortgage debt against total value, per property and across the portfolio. A schedule that shows 90% leverage on every door tells its own story.
- Debt-service coverage — net operating income divided by annual debt service. Many lenders look for roughly 1.20–1.25x or better on investment property; below 1.0x, the property does not pay for itself and your other income has to.
- Concentration — how much of your equity sits in one property, one market, or one tenant. Diversified equity reads as resilience.
You do not have to print these ratios — the columns above let any lender compute them. Filling the schedule in completely is what makes the math possible, and a schedule the reader can verify beats a summary they have to take on faith.
Common mistakes on an REO schedule
- Reporting gross rent as NOI. Net operating income is rent minus operating expenses — taxes, insurance, maintenance, management — before debt service. Inflated NOI is the fastest credibility loss on the page.
- Leaving out HELOCs and second liens. Equity is value minus all debt against the property, not just the first mortgage.
- Omitting the primary residence. Lenders expect every property; income columns simply stay blank for your home.
- Values that never move. A schedule where every value is the purchase price — or a suspiciously round number — invites an appraisal conversation.
- A schedule that disagrees with the PFS. The real estate totals here must match the real estate lines on your personal financial statement.
Questions, answered
What is a schedule of real estate owned?
A per-property listing of the real estate you own: value, mortgage debt, ownership, and cash flow. Lenders use it to see how leveraged your portfolio is and whether it feeds or drains your ability to service new debt.
What debt-service coverage do lenders want to see?
Practice varies by lender and property type, but roughly 1.20x to 1.25x NOI over annual debt service is a common floor for investment property. The schedule gives the reader both numbers per property, so compute yours before they do.
Do I include my primary residence?
Yes — lenders expect every property, including your home. Income-related columns simply stay blank for a residence that produces no rent.
What counts as net operating income?
Rental income minus operating expenses — taxes, insurance, maintenance, management — before mortgage payments. Debt service is listed separately so the lender can compute coverage.
How do investors keep this schedule current?
Most rebuild it by hand every time a lender asks. LivePFS keeps the same schedule current automatically — properties, balances, and cash-flow figures in one statement that refreshes daily.
General information, not legal, tax, or financial advice.
A schedule that updates itself
Connect your accounts read-only, add your properties once, and LivePFS keeps the real estate schedule — values, balances, cash flow — current inside a lender-ready statement.
Invitation-only while we onboard new borrowers. $190/year once you’re in.